When people think about life insurance, they often associate it with protection for their loved ones. While that remains an important purpose, life insurance can also be part of a broader financial plan. Alongside savings, investments and other financial goals, the right coverage can help create stability and support the plans you are building for […]
Why Your Roof’s Age Can Affect Your Home Insurance Rates!
Why Your Roof’s Age Can Affect Your Home Insurance Rates!
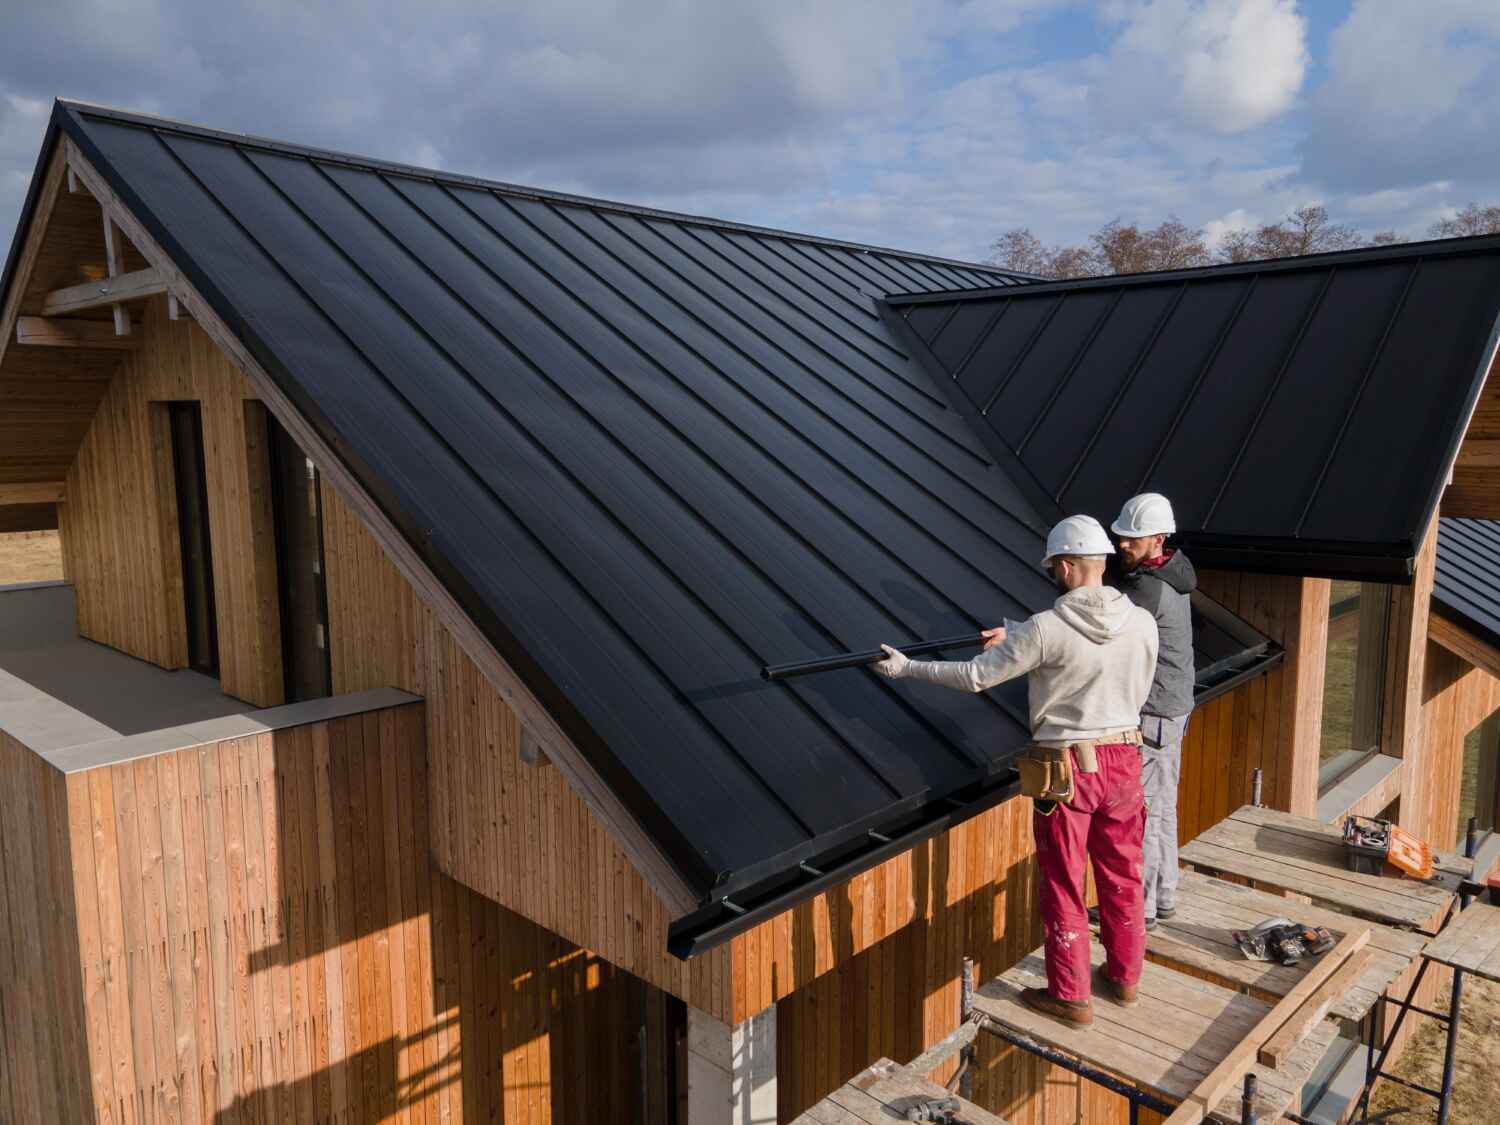
Your roof is your home’s first shield against wind, rain, hail and heat. When a roof gets old, it struggles to do that job. That is why many insurers look closely at roof age when they set your price or even when they agree to write the policy.
Older Roofs Mean Higher Risk
An older roof has more possibility to leak, lose shingles or fail in a storm. Water damage spreads fast and costs a lot to fix. Because the odds of a claim go up as a roof wears out, the price you pay for insurance can go up, too.
Material and Age Both Matter
Not all roofs age the same. A metal roof ages differently from an asphalt shingle roof. Tile and slate age differently, too and local weather plays a role. Sun, snow, and salt air all change how fast a roof wears. Insurers consider both the type and the age, plus the roof’s shape and how it was installed.
How Roof Age Can Change Your Policy?
If your roof is older, your insurer may:
- Offer a higher price than a similar home with a newer roof.
- Set a special wind or hail deductible on older roofs.
- Pay based on “actual cash value” (value after wear and tear) instead of “replacement cost” (brand‑new materials). That can mean a smaller claim check.
- Ask for proof of updates.
Smart Ways to Keep Costs in Check
- Keep records: permits, invoices and photos after repairs or a new roof.
- Do basic care: clean gutters, fix loose shingles, trim branches.
- Ask about roof credits: impact‑resistant shingles, water shields, or better vents may help.
- Get an inspection if you’re unsure of the roof’s age or condition.
- If you are home shopping, ask for the roof’s install year, materials, and any warranty.
Timing a Replacement
If your roof is near the end of its life, plan the swap before peak storm season if you can. A timely upgrade can steady your rate and cut the chance of leaks.
Home insurance protects your biggest asset. A strong roof lowers the chance of a claim and can help you qualify for better coverage at a better price. Hiding a roof’s age can backfire during a claim. Being open and proactive keeps both your home and your policy in good shape.
Protect Your Business: Proven Tips to Minimize Risks and Expenses!
Running a business involves balancing growth opportunities with everyday challenges. From managing expenses and protecting employees to handling unexpected disruptions, risks can appear at any stage of your journey. While every business faces uncertainty, smart planning can help reduce financial pressure and create a stronger foundation for long-term success. 1. Understand your biggest business risks […]
K & J Insurance LLC
We extend coverage to individuals and businesses throughout Indiana in Winslow, Otwell, Oakland City and Monroe City and surrounding areas.
Personal Insurance
Business Insurance
Medicare
© 2026 K & J Insurance LLC Designed by Amplispot
Your roof is your home’s first shield against wind, rain, hail and heat. When a roof gets old, it struggles to do that job. That is why many insurers look closely at roof age when they set your price or even when they agree to write the policy.
Older Roofs Mean Higher Risk
An older roof has more possibility to leak, lose shingles or fail in a storm. Water damage spreads fast and costs a lot to fix. Because the odds of a claim go up as a roof wears out, the price you pay for insurance can go up, too.
Material and Age Both Matter
Not all roofs age the same. A metal roof ages differently from an asphalt shingle roof. Tile and slate age differently, too and local weather plays a role. Sun, snow, and salt air all change how fast a roof wears. Insurers consider both the type and the age, plus the roof’s shape and how it was installed.
How Roof Age Can Change Your Policy?
If your roof is older, your insurer may:
- Offer a higher price than a similar home with a newer roof.
- Set a special wind or hail deductible on older roofs.
- Pay based on “actual cash value” (value after wear and tear) instead of “replacement cost” (brand‑new materials). That can mean a smaller claim check.
- Ask for proof of updates.
Smart Ways to Keep Costs in Check
- Keep records: permits, invoices and photos after repairs or a new roof.
- Do basic care: clean gutters, fix loose shingles, trim branches.
- Ask about roof credits: impact‑resistant shingles, water shields, or better vents may help.
- Get an inspection if you’re unsure of the roof’s age or condition.
- If you are home shopping, ask for the roof’s install year, materials, and any warranty.
Timing a Replacement
If your roof is near the end of its life, plan the swap before peak storm season if you can. A timely upgrade can steady your rate and cut the chance of leaks.
Home insurance protects your biggest asset. A strong roof lowers the chance of a claim and can help you qualify for better coverage at a better price. Hiding a roof’s age can backfire during a claim. Being open and proactive keeps both your home and your policy in good shape.
Disclosure:
The content provided within this website is presented for information purposes only. This is not a commitment to lend or extend credit. Information and/or dates are subject to change without notice. All loans are subject to credit approval. Other restrictions may apply. Mortgage loans may be arranged through third party providers.
© 2026 Art Ramirez RELO Designed by Amplispot
Your roof is your home’s first shield against wind, rain, hail and heat. When a roof gets old, it struggles to do that job. That is why many insurers look closely at roof age when they set your price or even when they agree to write the policy.
Older Roofs Mean Higher Risk
An older roof has more possibility to leak, lose shingles or fail in a storm. Water damage spreads fast and costs a lot to fix. Because the odds of a claim go up as a roof wears out, the price you pay for insurance can go up, too.
Material and Age Both Matter
Not all roofs age the same. A metal roof ages differently from an asphalt shingle roof. Tile and slate age differently, too and local weather plays a role. Sun, snow, and salt air all change how fast a roof wears. Insurers consider both the type and the age, plus the roof’s shape and how it was installed.
How Roof Age Can Change Your Policy?
If your roof is older, your insurer may:
- Offer a higher price than a similar home with a newer roof.
- Set a special wind or hail deductible on older roofs.
- Pay based on “actual cash value” (value after wear and tear) instead of “replacement cost” (brand‑new materials). That can mean a smaller claim check.
- Ask for proof of updates.
Smart Ways to Keep Costs in Check
- Keep records: permits, invoices and photos after repairs or a new roof.
- Do basic care: clean gutters, fix loose shingles, trim branches.
- Ask about roof credits: impact‑resistant shingles, water shields, or better vents may help.
- Get an inspection if you’re unsure of the roof’s age or condition.
- If you are home shopping, ask for the roof’s install year, materials, and any warranty.
Timing a Replacement
If your roof is near the end of its life, plan the swap before peak storm season if you can. A timely upgrade can steady your rate and cut the chance of leaks.
Home insurance protects your biggest asset. A strong roof lowers the chance of a claim and can help you qualify for better coverage at a better price. Hiding a roof’s age can backfire during a claim. Being open and proactive keeps both your home and your policy in good shape.
Disclosure:
The content provided within this website is presented for information purposes only. This is not a commitment to lend or extend credit. Information and/or dates are subject to change without notice. All loans are subject to credit approval. Other restrictions may apply. Mortgage loans may be arranged through third party providers.
© 2026 Art Ramirez RELO Designed by Amplispot